Lumexa Imaging Holdings (NASDAQ: LMRI) operates outpatient diagnostic-imaging centers, providing MRI, CT and other scans that help doctors diagnose illness. This is a substantial healthcare business, not a pre-revenue IPO: its November 10 report described more than 5,000 team members and 190 centers. For the quarter ended September 30, 2026, revenue reached $272.0 million and net income was $7.2 million. Balance-sheet borrowings totaled $837.1 million at quarter-end, excluding separately reported lease liabilities. That combination of real demand, improving bottom-line results and meaningful debt makes its rally worth examining.
A better earnings picture meets a battered IPO
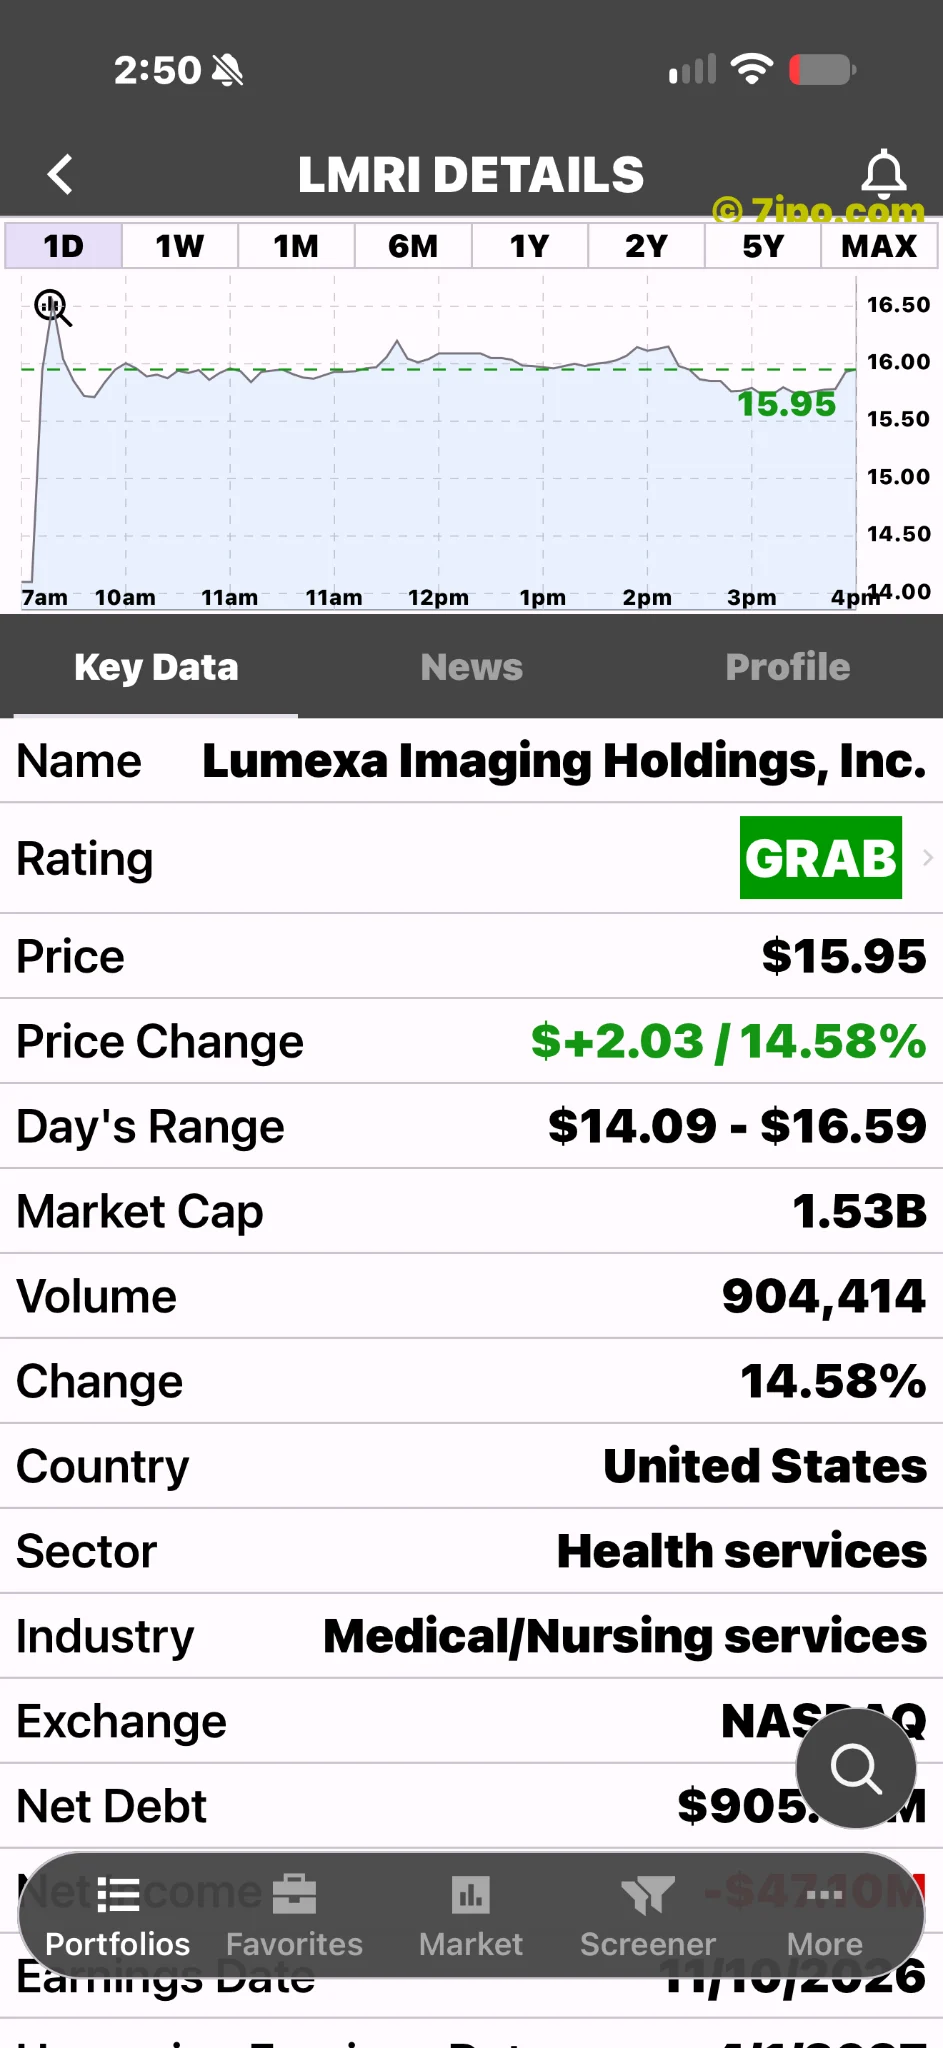
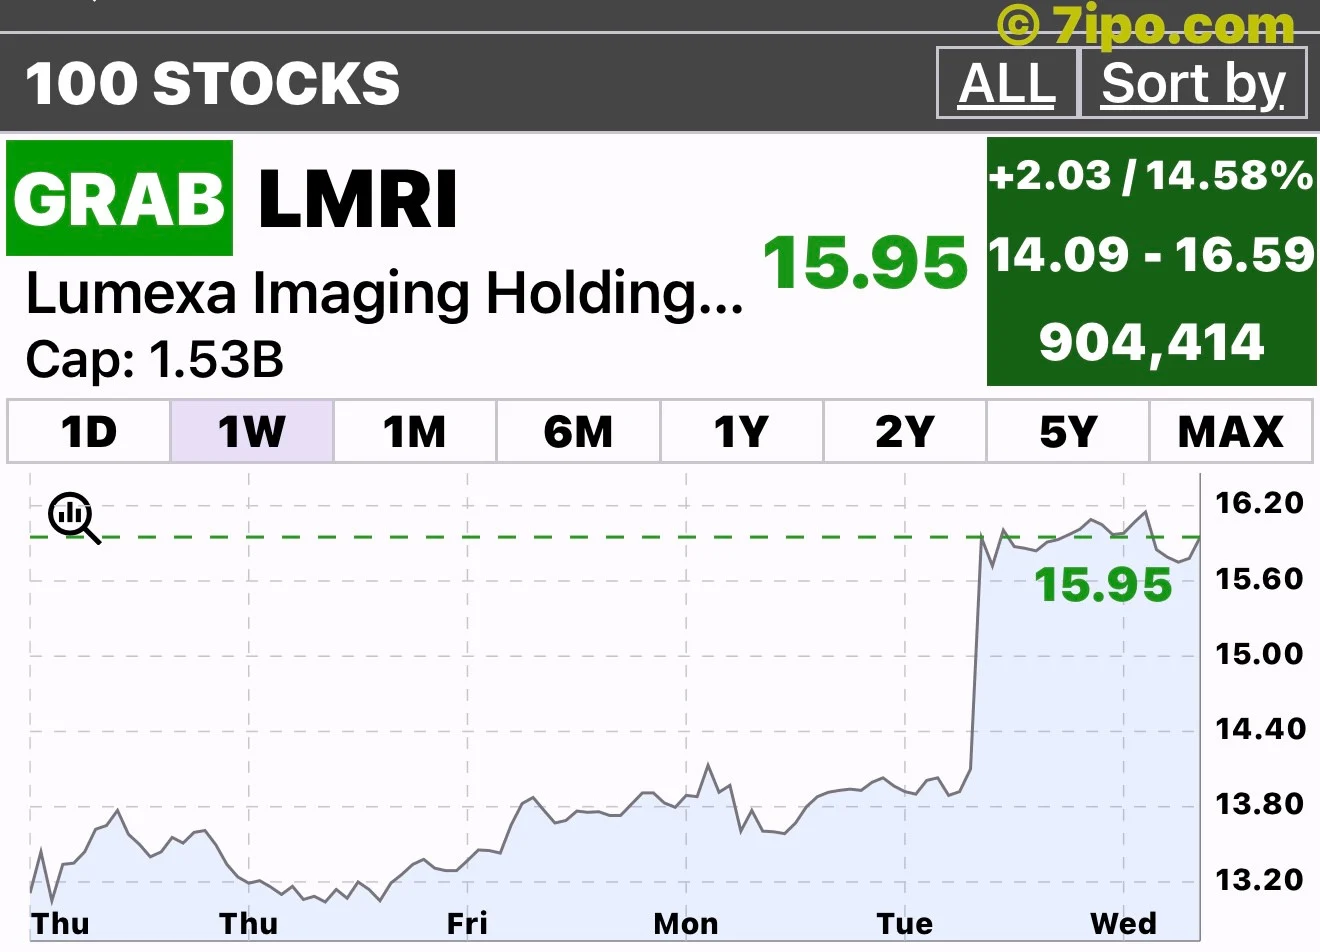
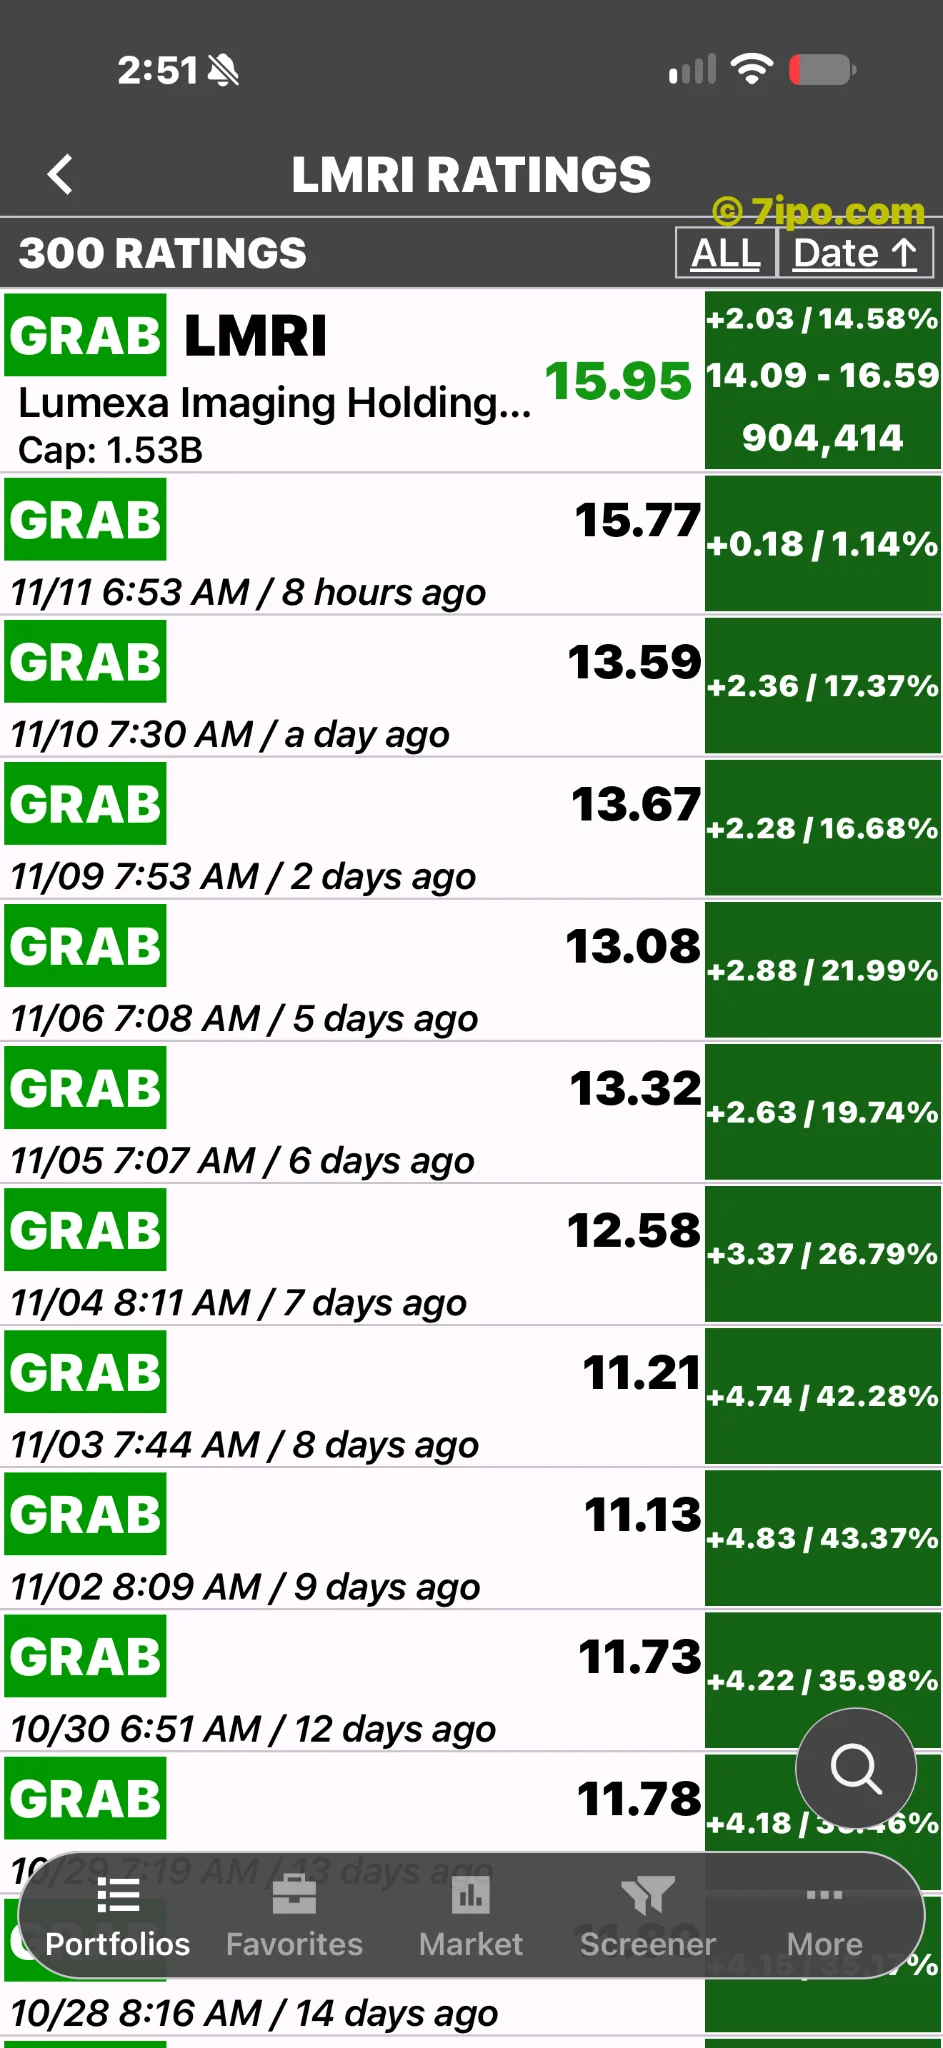
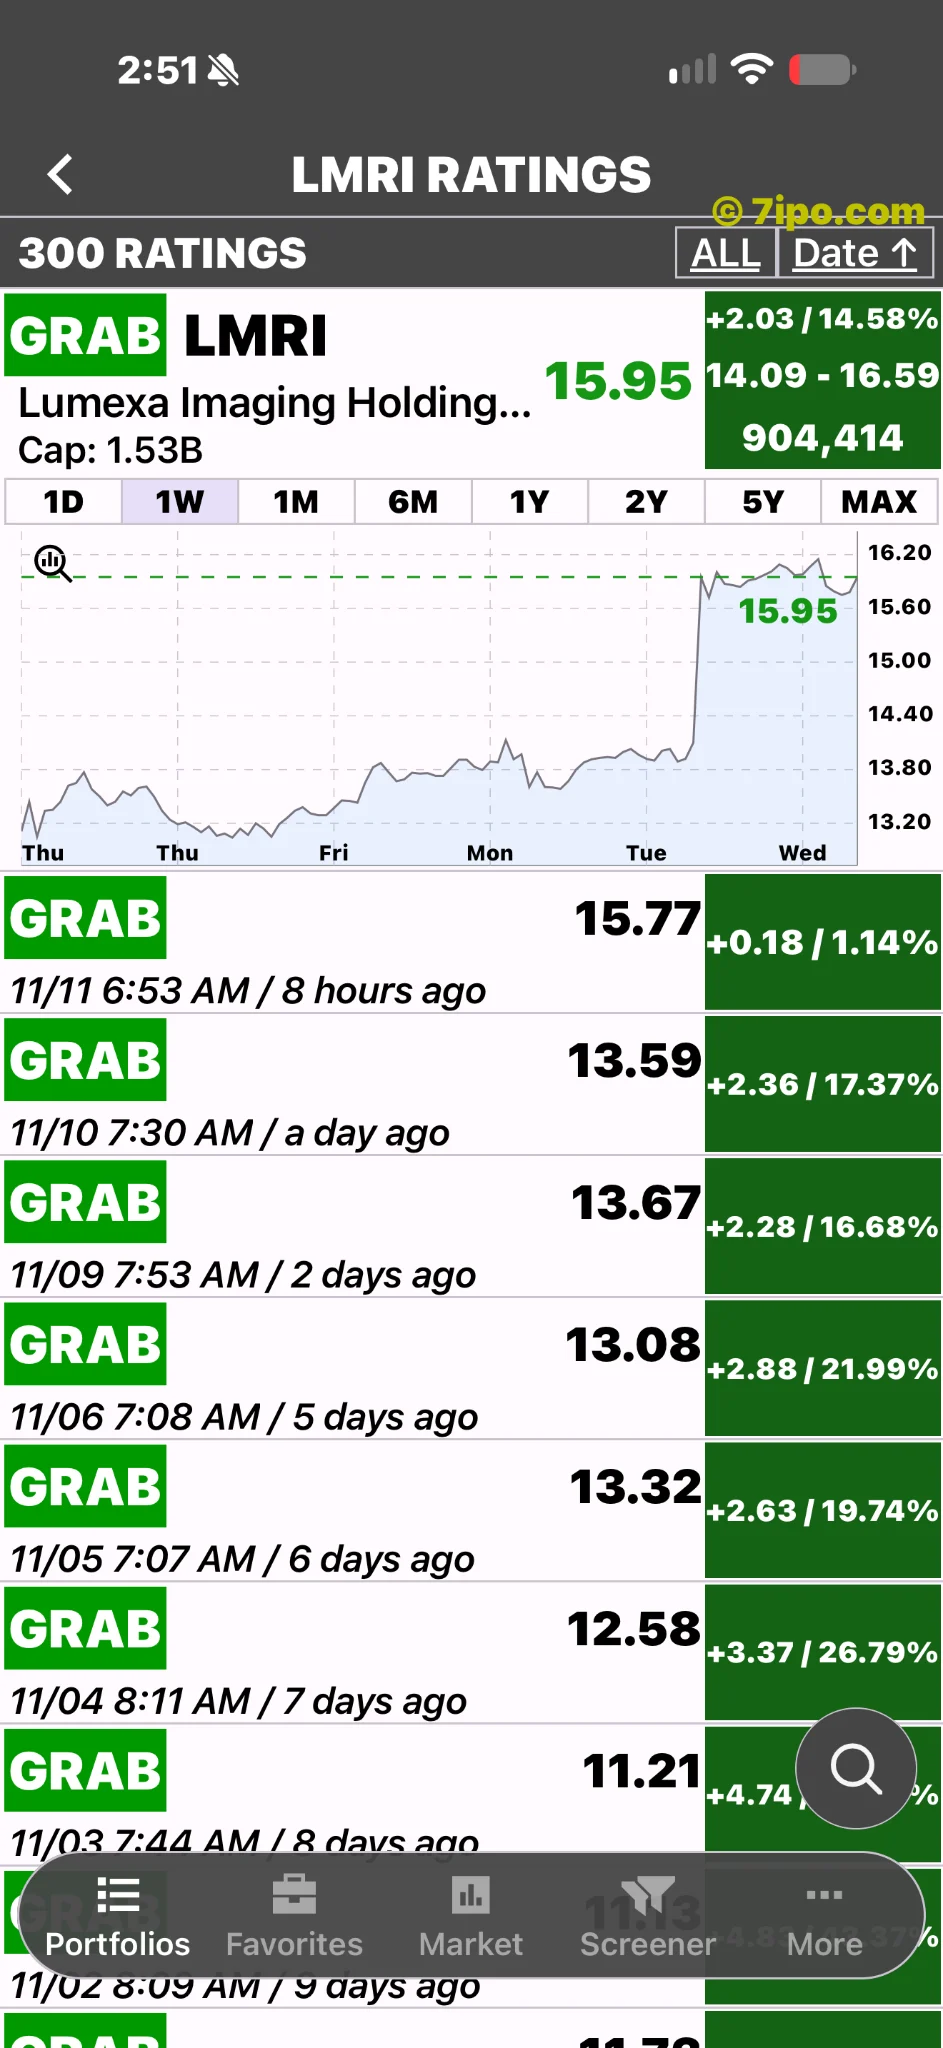
Eric’s November 11 screenshot shows LMRI at $15.95, up +$2.03 or 14.58%, with displayed volume of 904,414 shares. These are screenshot observations, not a live quote or an independently verified official closing price. The daily chart shows a sharp early rise followed by trading near $16, rather than an uninterrupted climb throughout the session.
The fresh company news was Lumexa’s third-quarter earnings release on November 10. Revenue rose 5% year over year, while the company moved from a $3.5 million net loss to a $7.2 million profit. Advanced imaging, including MRI and CT, offered an encouraging detail: advanced-procedure volume rose 7.9%, with same-center advanced volume up 6.6%.
Those results provide a credible backdrop for renewed interest. They do not prove that every buyer was responding to the same catalyst. The distinction matters: a news event can explain why a stock deserves attention without establishing a single cause for every price move.
The profit improvement needs a closer reading
The welcome development is that Lumexa produced a profitable quarter while expanding sales. The caution is that this was not a uniform improvement across the income statement. Operating income declined to $28.1 million from $30.3 million, while interest expense fell to $15.7 million from $30.6 million. Lower financing costs materially helped the bottom line.
There is a similar qualification to the higher outlook. Lumexa increased its full-year adjusted earnings-per-share forecast to $0.86–$0.90 from $0.71–$0.77, citing a lower assumed tax rate. Revenue guidance was unchanged, as was the midpoint of adjusted EBITDA guidance. A tax-assisted earnings upgrade is useful, but it should not be presented as a sudden surge in underlying sales expectations.
Borrowings also deserve space beside the good news. The $837.1 million figure combines current and noncurrent debt on September 30. Cash was $90.0 million. Finance leases of $54.8 million and operating leases of $82.7 million were reported separately. These distinctions keep debt, leases and cash from being collapsed into a misleading single number.
Six months of recovery, one month of acceleration
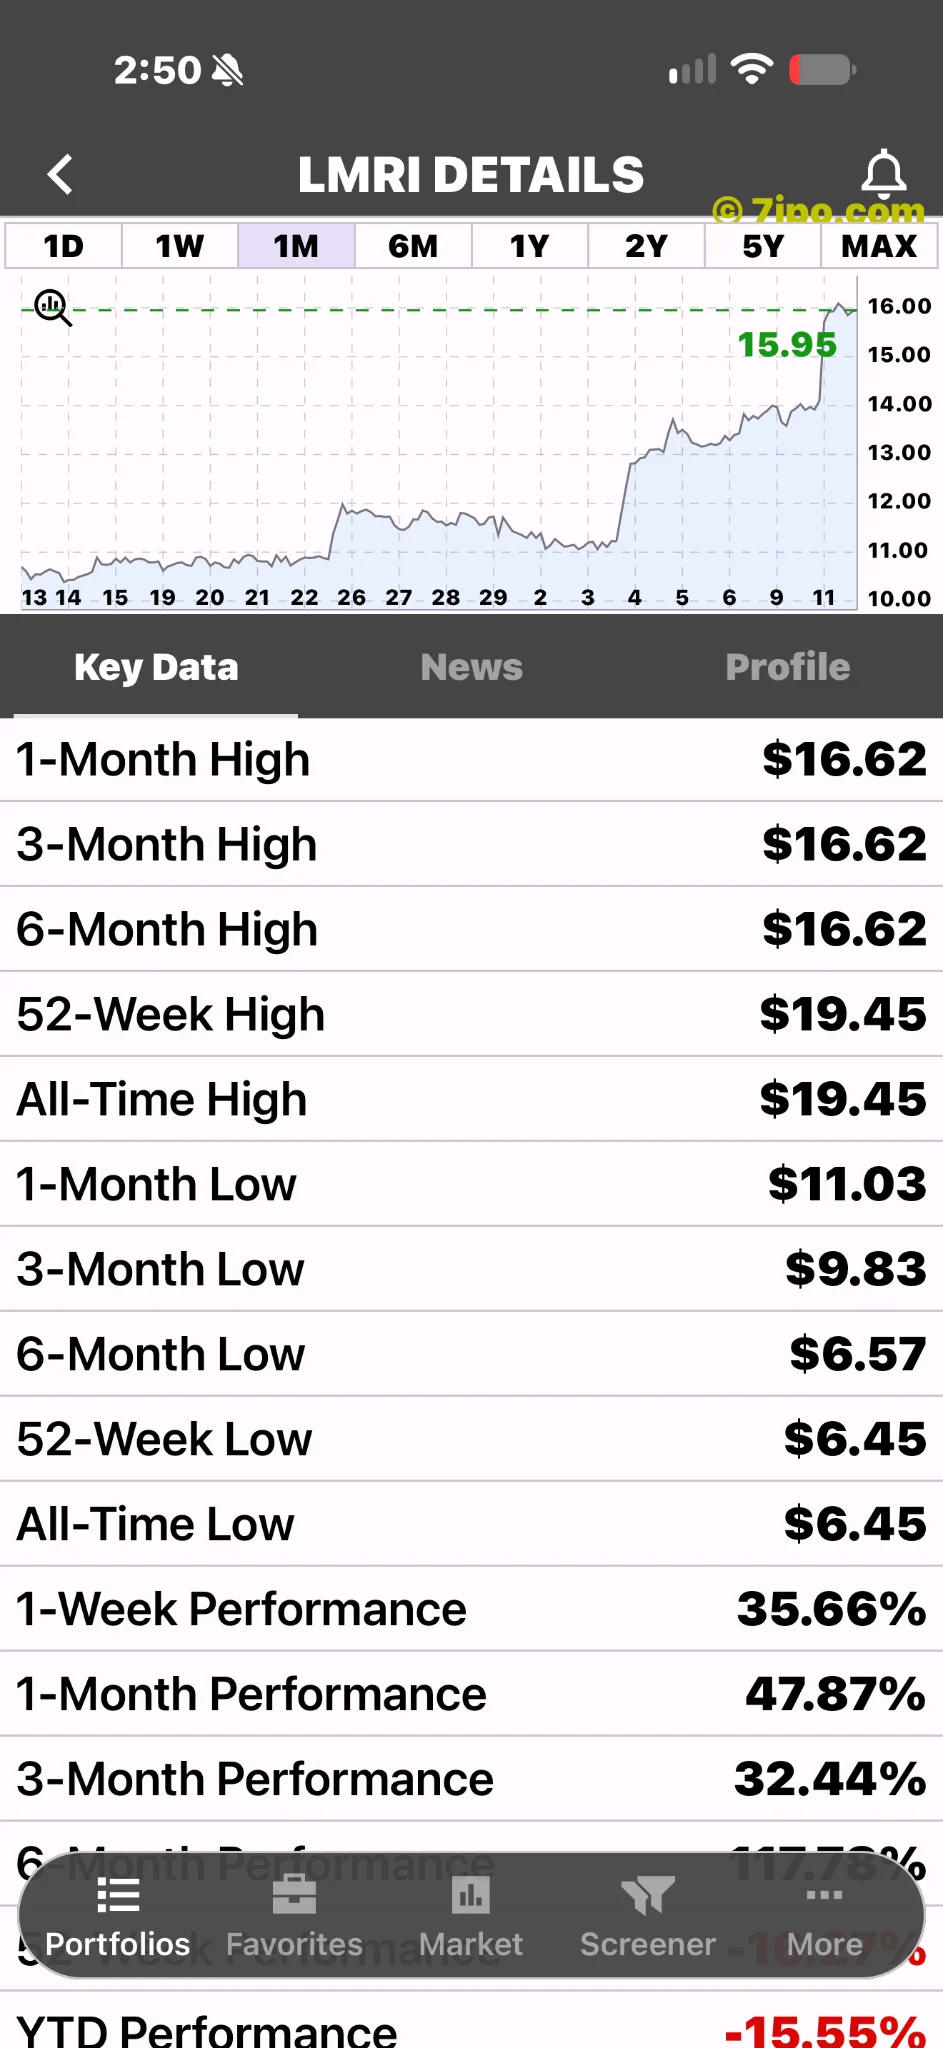
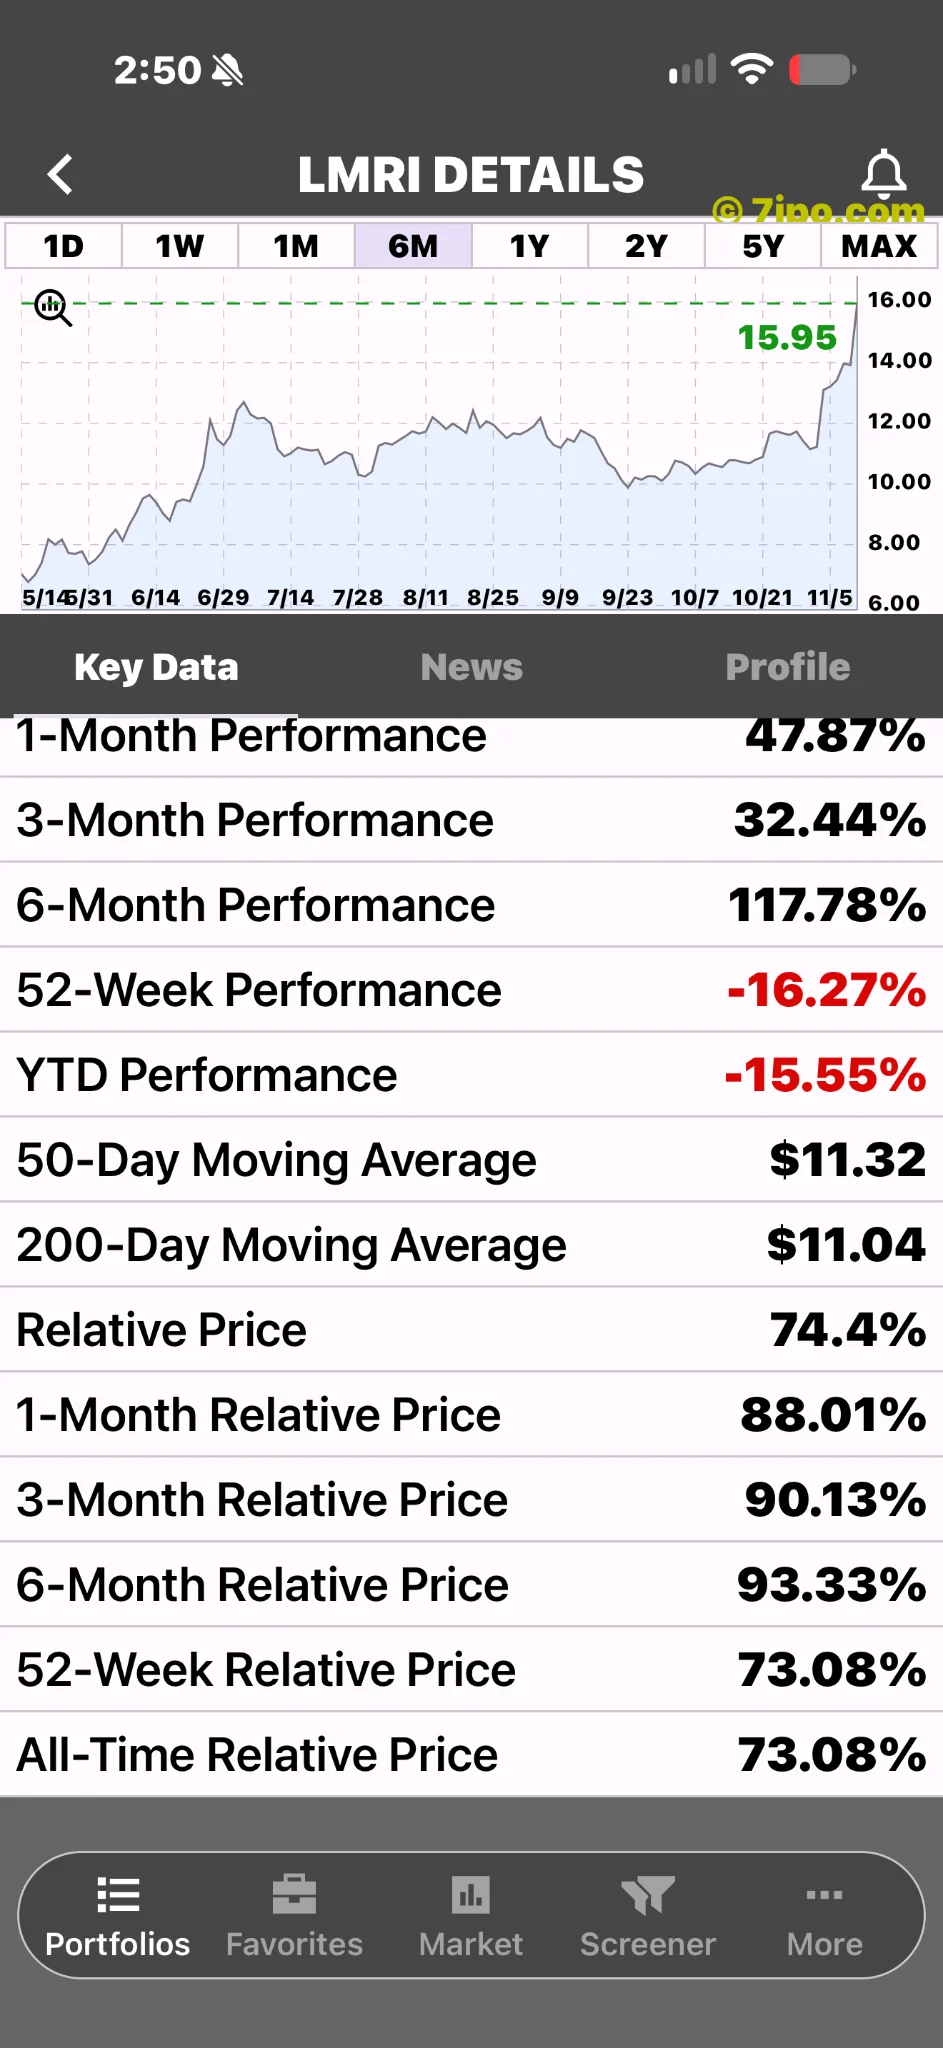
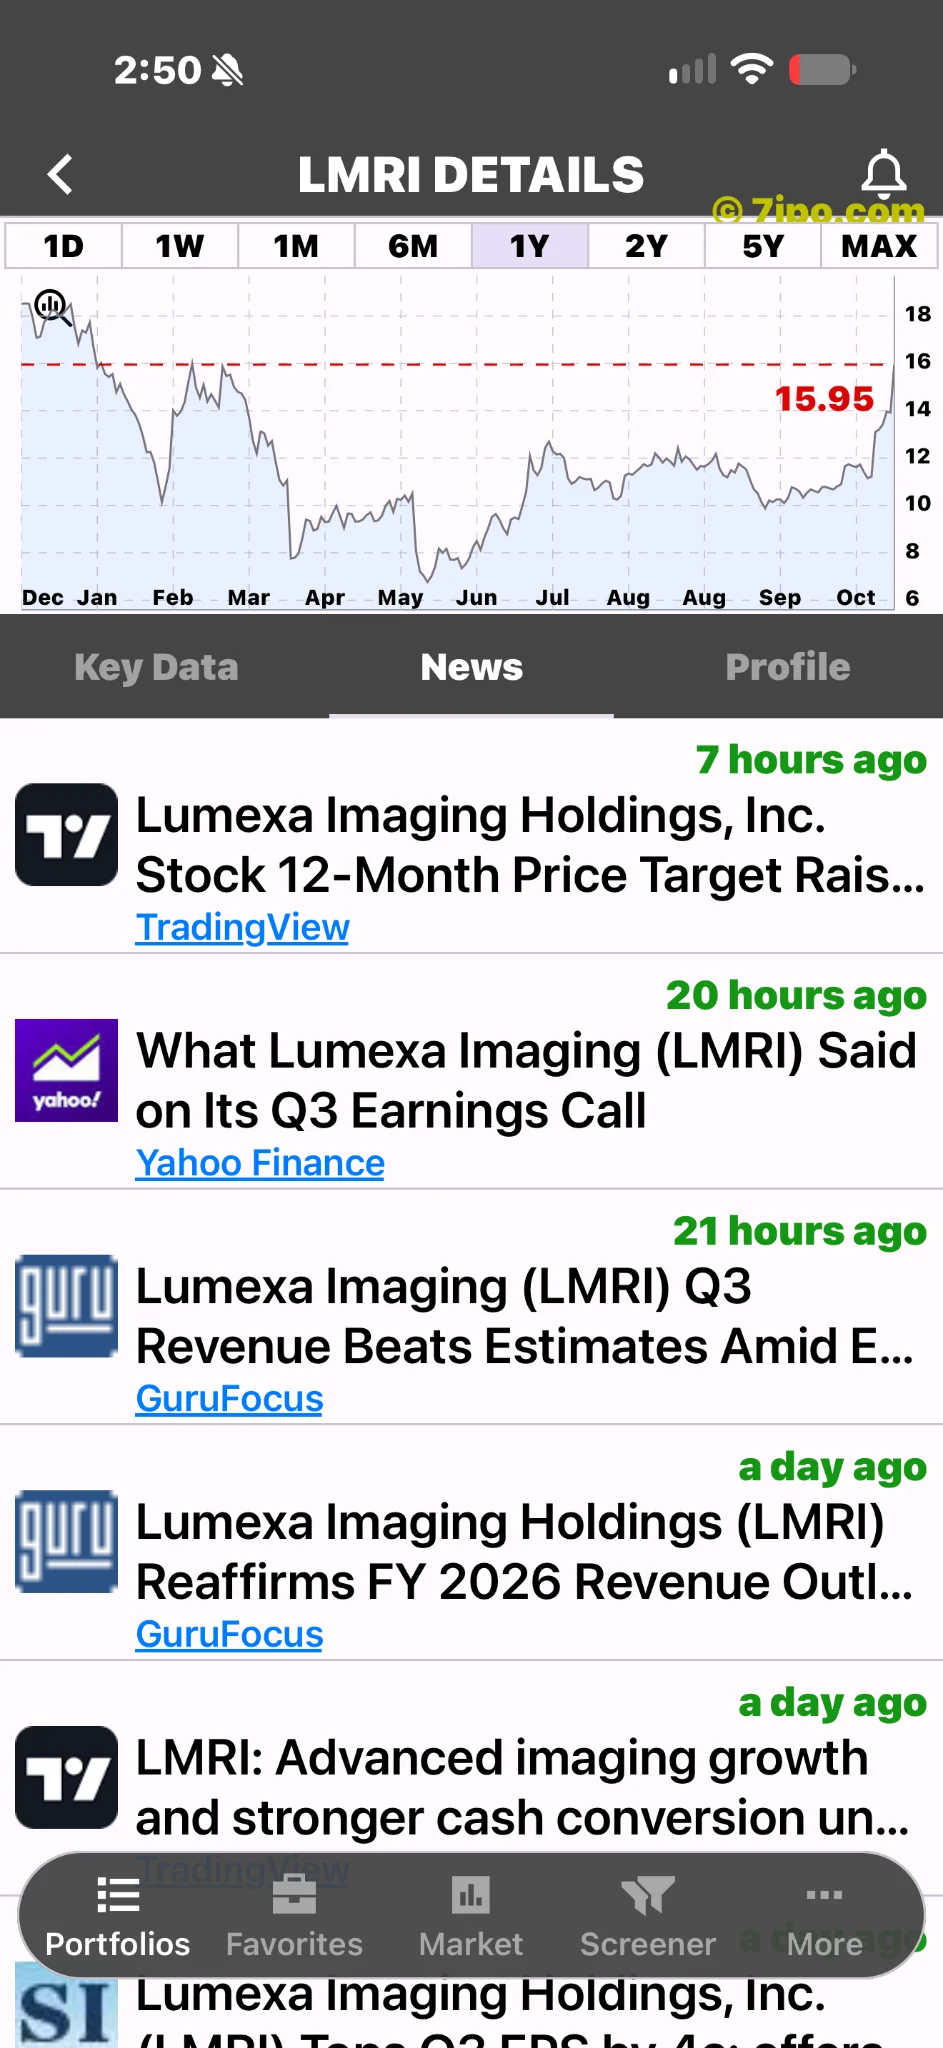
The supplied six-month chart shows a broad recovery from the spring lows, interrupted by a long, uneven stretch around $10–$12. The most recent month looks different: the advance becomes steeper, with successive upward steps and a final jump toward $16.
The app explicitly displays gains of 47.87% over one month, 32.44% over three months and 117.78% over six months. Those are app-reported snapshot metrics, not returns independently recalculated for this article. Together with the chart, they describe an accelerating recovery rather than a stock that has risen smoothly since its listing.
Lumexa priced its IPO at $18.50 per share and began Nasdaq trading on December 11, 2025. At the screenshot’s $15.95, it remained approximately 13.8% below that offering price. A powerful rebound and a disappointing result for an original IPO buyer can both be true.
What would make the recovery more convincing
The next test is whether healthy imaging demand translates into sustained operating-income growth, not merely a better result after lower interest costs or taxes. Debt management matters too. A stronger chart can signal changing expectations, but it cannot erase obligations from the balance sheet.
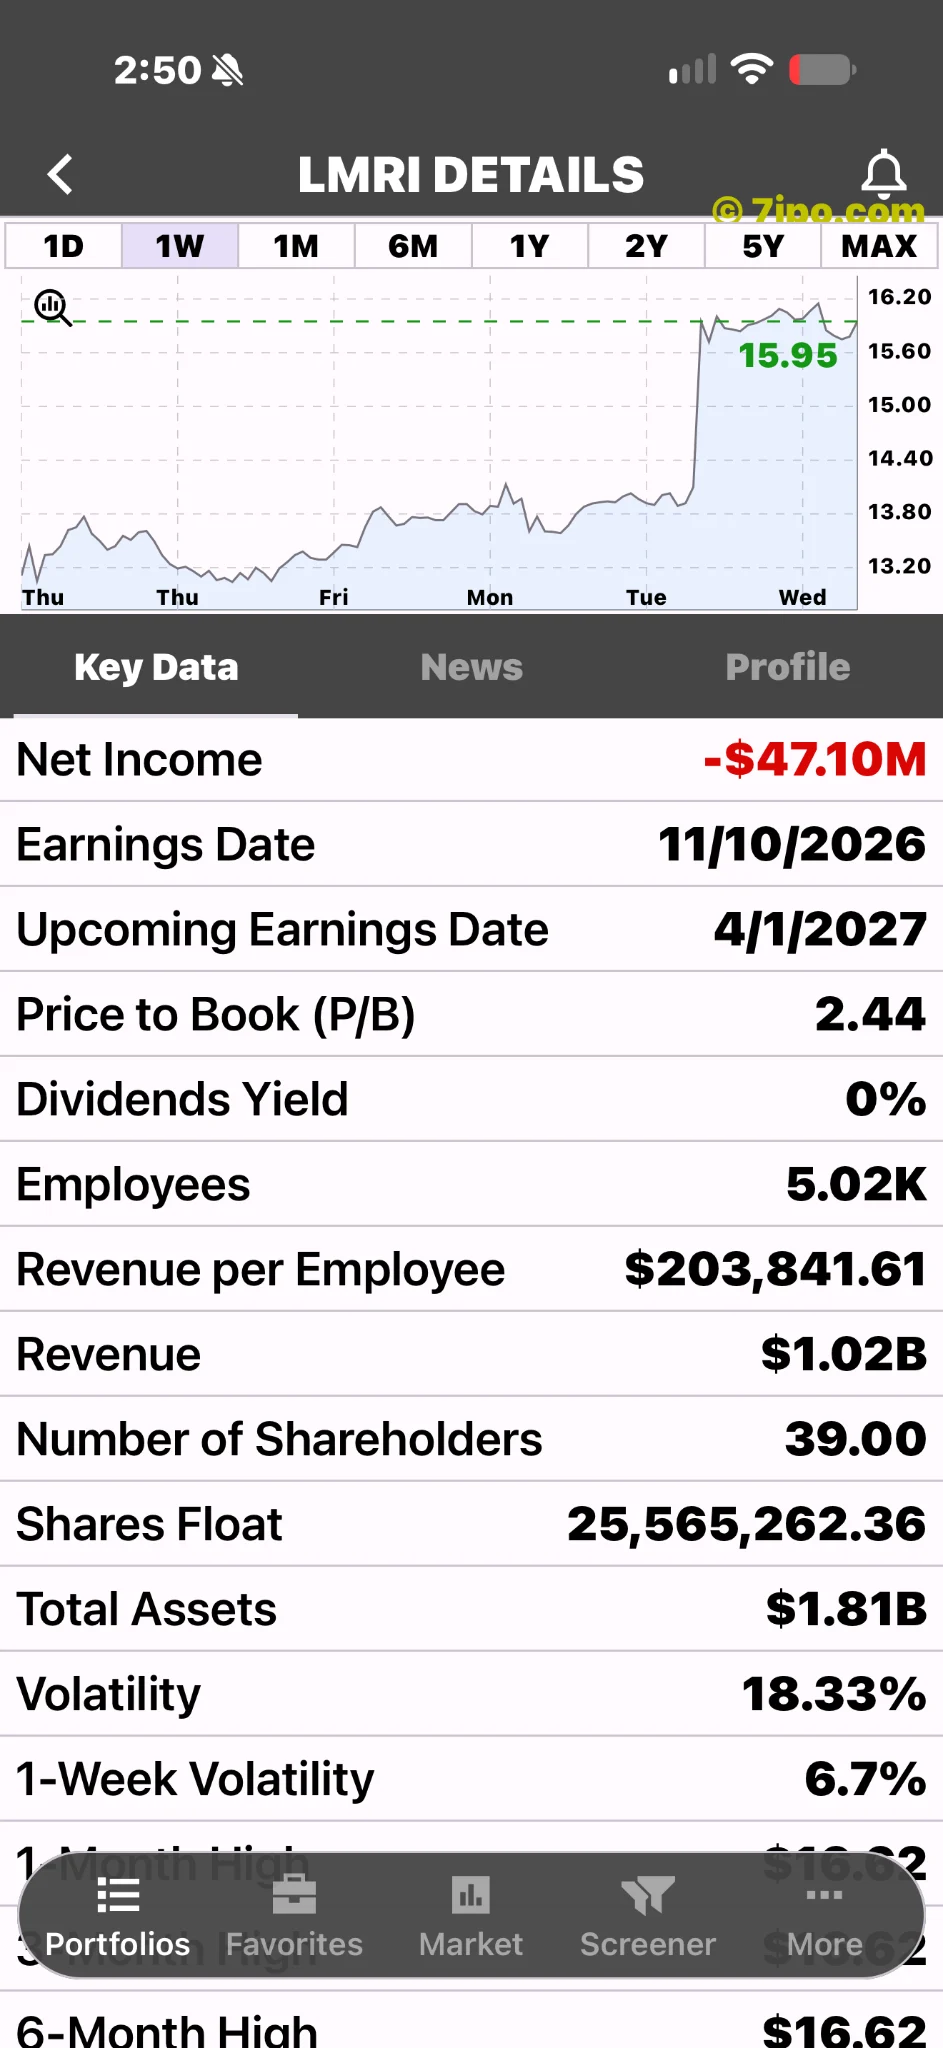
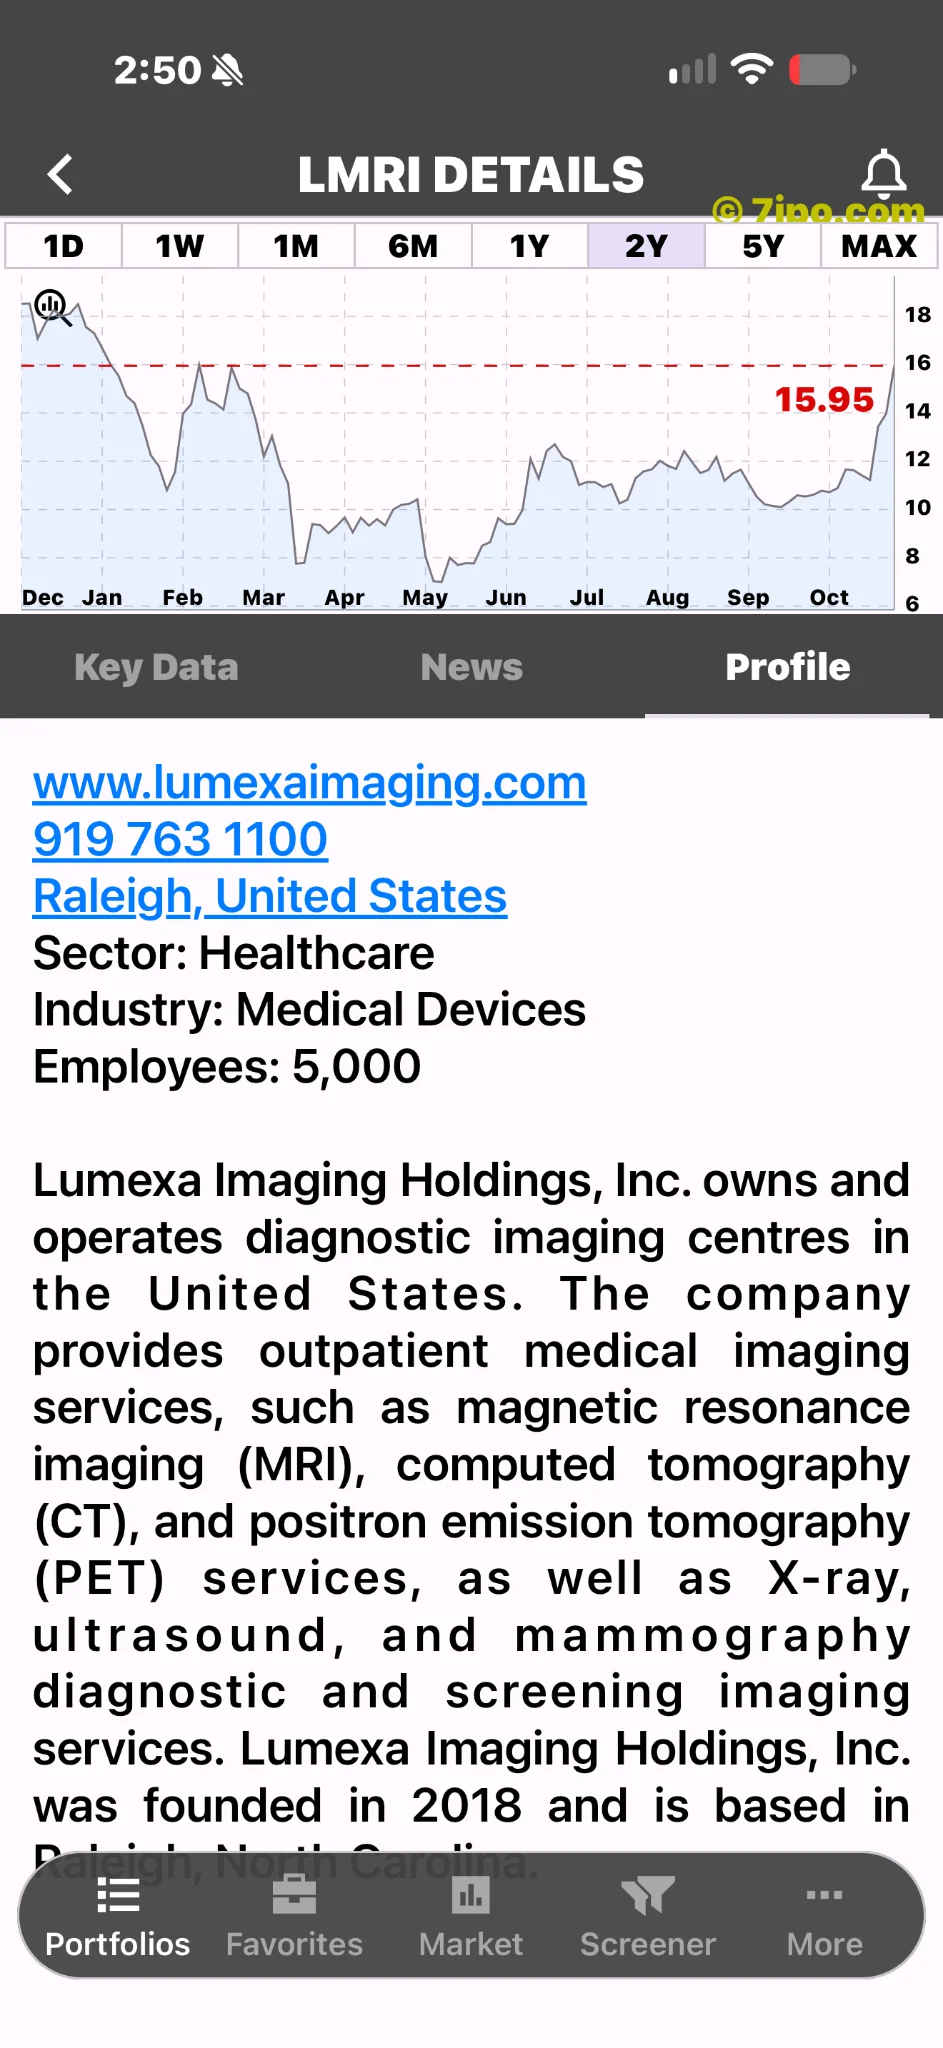
All nine supplied images appear with this story, including the profile, news and rating-history views. Some app fundamentals have unspecified reporting periods: the displayed $1.02 billion revenue and $47.10 million loss must not be mistaken for the latest quarter. The dated company release supplies the quarterly figures above. “GRAB” is the app’s own label, not this article’s recommendation.
Explore recent listings with IPO-Stocks.app. Screenshots retain their visible 7ipo.com provenance. This article is informational, not personalized investment advice.